If you've been waiting on the sidelines because of interest rates, here's something a lot of buyers don't realize. In today's Middle Tennessee market, the seller may be willing to help pay your rate down.
The market has shifted. A few years ago, buyers were writing offers over asking price and waiving everything just to get a house. Today it's a different story. Redfin reported that Nashville was one of the strongest buyer's markets in the country this summer, with more than twice as many sellers as buyers. Homes are sitting longer, and sellers are getting more flexible.
One of the biggest ways that shows up is seller concessions. According to Redfin, about 3 out of 4 Nashville-area home sales in May 2026 included a concession from the seller. That was the highest share of any major market they track.
So what does that mean for you? Let's break it down.
What is a seller concession?
A seller concession is money the seller agrees to put toward your costs at closing. Instead of just knocking the price down, the seller gives you a credit you can use for things like:
Closing costs (title, appraisal, lender fees, prepaid taxes and insurance)
Buying down your interest rate
In some cases, both
Your real estate agent negotiates this as part of your offer. My job is to show you and your agent the best way to use it.
Price cut or seller credit: which helps more?
A lot of buyers assume a lower price is always the better deal. Sometimes it is. But when rates are higher, a seller credit used toward your rate can lower your monthly payment more than the same amount taken off the price.
Think about it this way. Taking a few thousand dollars off the price only lowers your loan amount by that much, so your payment barely moves. That same money used to buy down your rate can make a bigger difference in your monthly payment. Every situation is different, so I always run the numbers both ways before you make an offer.
Three ways to use a seller concession
1. A temporary buydown (like a 2-1 buydown)
With a 2-1 buydown, the seller's credit pays to lower your rate by 2% in the first year and 1% in the second year. In year three, your rate goes to the full note rate for the rest of the loan. This gives you some breathing room in the first couple years while you get settled. It's also a nice cushion if rates drop later and you decide to refinance.
2. A permanent buydown
This is where the credit pays for discount points that lower your rate for the life of the loan. It costs more up front than a temporary buydown, but the savings last as long as you keep the loan. This can make a lot of sense if you plan to stay in the home for a while.
3. Closing cost help
If cash to close is the bigger hurdle, you can put the credit toward your closing costs instead. That means less money out of your pocket on closing day. For first-time buyers especially, this can be what makes buying possible right now.
How much can a seller give?
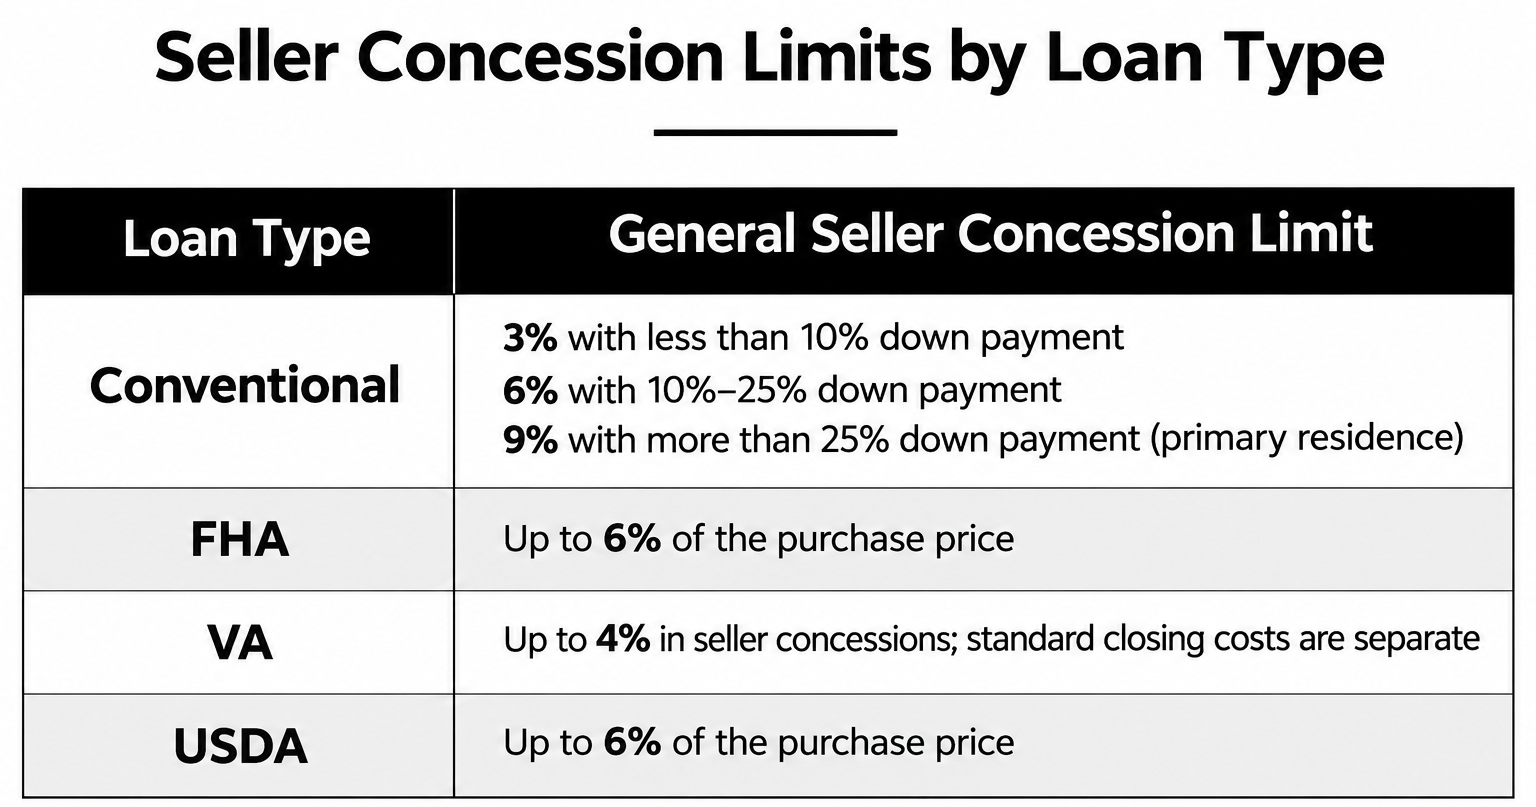
These are general guidelines and can vary, so we'll confirm what applies to your specific loan before you write an offer.
Tips for using concessions the right way
Talk to me before you make an offer. The best time to plan a buydown is before you write the contract, not after.
Make sure your agent asks for it. In this market, asking for a concession is normal. The worst a seller can say is no.
Don't ask for more than you can use. If the credit is more than your allowed costs, you can't take the extra as cash. We'll figure out the right number together.
Watch the appraisal. If a concession is built into a higher price, the home still needs to appraise at that price.
The bottom line
You don't have to wait for rates to drop to make a smart move. In a market where sellers are willing to help, the right concession can lower your payment, cut your cash to close, or both.
I help buyers all over Middle Tennessee, including Lebanon, Mount Juliet, Murfreesboro, and Nashville. If you're thinking about buying, let's sit down and run the numbers so you know exactly how to use a seller credit before you start making offers.
Get in touch here or call me at (615) 636-3796.
This article is for general information only and is not a commitment to lend. Loan programs, concession limits, rates, and terms are subject to change and to credit approval.